How to save money on a personal loan: Lower your APR
A few percentage points on your APR can cost you hundreds of dollars. The good news is that you can take steps to pull that rate down before you apply for a personal loan. Certain loan features will cut your costs even further. In this article, we’ll explore what affects your APR and how you can lower it.
The 4 factors that affect your APR
Here are four main variables that determine the rate you get with:
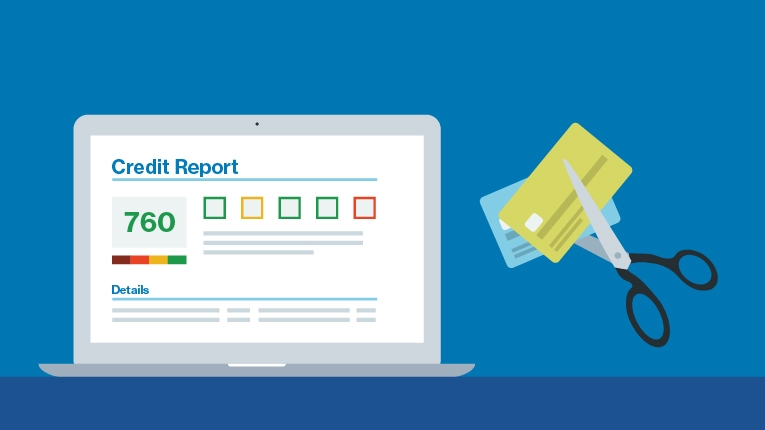
Your credit profile. Your credit history shows lenders how much risk you carry. Before you apply, check your credit report for mistakes at AnnualCreditReport.com. Fixing errors is free and can instantly boost your credit score. A stronger credit score can get you lower rates.
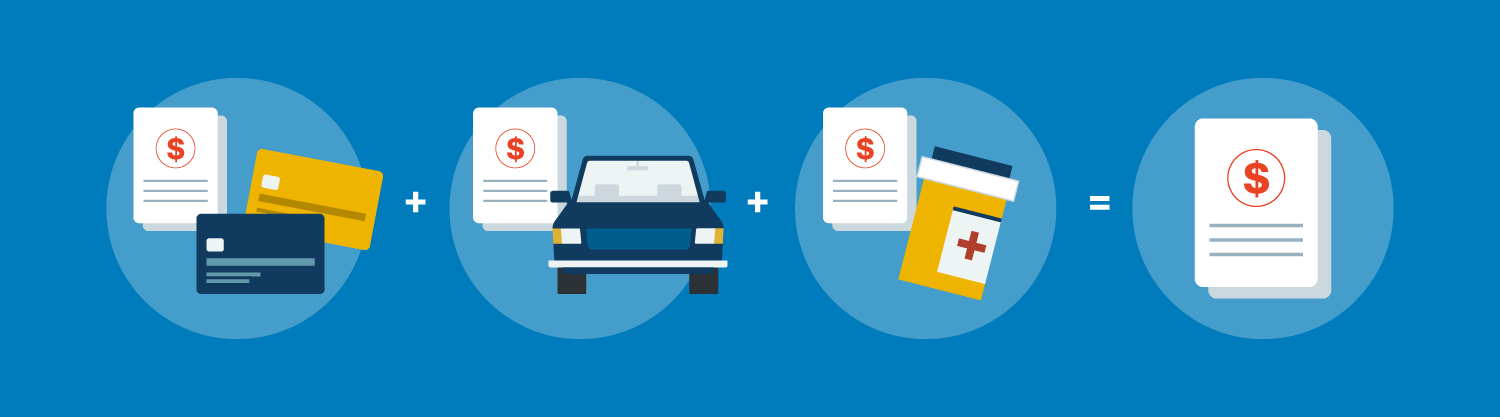
Your debt-to-income (DTI) ratio. Your DTI ratio compares your monthly debt payments to your total income. Paying down existing bills before you apply can drop this number quickly. Aim to keep your DTI ratio under 30%.
Your loan term. Shorter terms usually mean lower interest rates, but higher monthly payments. Longer terms can shrink your monthly bill, but it costs you way more in total interest. Pick the shortest timeline your monthly budget can comfortably handle.
Your loan amount. How much you borrow influences your APR offer, depending on the lender. Stick to what you actually need rather than rounding up.
Six ways to lower your APR
Here are six moves that can bring your APR down:
Pay down credit card balances. Trimming credit card balances can boost your credit score and drop your DTI ratio at the exact same time. That double win can push your APR in the right direction.
Build a clean payment history. Make every single payment on time in the months leading up to your application. Consistency is key.
Keep old accounts open. Closing an old card shortens your average credit history length, which hurts your credit score. If an old card doesn't charge fees, leave it open.
Check your rate. You should check your rate with multiple lenders. A soft pull is a light credit check that lets lenders show you real offers without hurting your credit score. This helps you see where you stand and potentially snag a better offer. With Happen Bank, you can check your rate in seconds. It also doesn’t affect your credit score.1,2
Apply with a co-borrower. Adding a creditworthy co-borrower can improve your overall creditworthiness. Just remember: you both share legal responsibility for the loan.
Borrow only what you need. Asking for less cash can land you a better APR. Don't borrow money you do not need.
Ways to save with a Happen Bank loan
If you take out a personal loan with Happen Bank, you can use these features to cut your costs even further:
Direct Pay APR discount. Happen Bank's Direct Pay option sends your loan funds straight to your qualifying creditors for you. Doing this nets you an APR discount between 0.75% and 8%.3
Zero prepayment penalties. You won't pay a dime in prepayment penalty fees for paying off your loan early. Every extra dollar you pay goes straight toward your balance. This shortens your loan timeline and wipes out potential future interest charges.
Finding the right rate for your situation
Most of the factors driving your APR are in your hands before you ever fill out an application. Even better, these moves compound: improving your credit score usually involves lowering your DTI ratio too. Once your numbers look solid, check your rates.
Frequently asked questions
How can I get a lower APR on a personal loan?
Pay down your credit card balances to lower your DTI ratio, and check your rate to shop around. If you are consolidating debt, Direct Pay at Happen Bank has a discount of 0.75% to 8% off your APR to help.3
Is APR or interest rate more important when comparing personal loans?
Always compare APRs. Your APR includes the interest rate plus upfront costs like origination fees, giving you the true, complete cost of the loan. Comparing one lender's base interest rate to another lender's APR can give you a misleading picture.
Does checking my APR with Happen Bank hurt my credit score?
No. Checking your rate with Happen Bank uses a soft pull (an initial credit review that doesn't hurt your credit profile), so your score stays safe. Your credit score is only affected if the loan is funded.2
Can I lower my personal loan APR after I've already taken out the loan?
Your APR is fixed for the entire life of the loan. However, you can lower your total cost by throwing extra cash at your principal balance. Happen Bank charges zero prepayment penalties, so every extra payment reduces your total interest.
Related terms
Disclosures
Between April 2026 and June 2026, 76% of Happen Personal Loans offers were generated in under a minute from the beginning of the application process.
Checking a rate through us generates a soft inquiry on a person's credit report, which does not impact that person's credit score. A hard credit inquiry, which may affect that person's credit score, only appears on the person's credit report if and when a loan is issued to the person.
The APR discounted rate is a discount that some customers may receive for taking out a loan to pay down existing qualifying debt paid directly by Happen Bank; such rate is discounted from the rate given for taking a full cash loan. Not all applicants will qualify for the discount. Any actual discount rate will be determined at the time of application. The best APR discounts may be available to borrowers with excellent credit. Advertised discounted rates are subject to change without notice.
You May Also Like