{noun} All monthly debt payments divided by monthly gross income, expressed as a percentage.
Debt-to-Income (DTI) Ratio
January 29, 20233 min read
What is Debt-to-Income (DTI) Ratio?
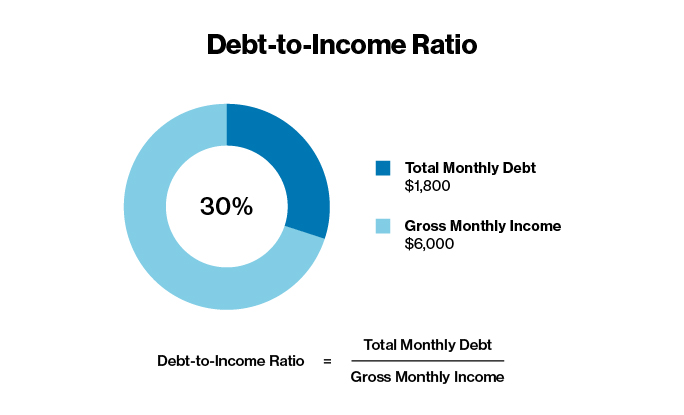
Your debt-to-income ratio is all your monthly debt payments divided by your gross monthly income, expressed as a percentage. In other words, it’s what you earn every month minus what you owe every month. This ratio is one way that lenders measure your ability to manage monthly payments and repay money you plan to borrow.
How Is Debt-to-Income Calculated?
Simply add up all your monthly debt payment obligations (such as housing, loans, and minimum credit card payments) and divide them by your monthly income before any deductions are taken out (i.e. your gross income). The resulting percentage is your DTI.
Why Is Debt-to-Income Important?
If you’re applying for new credit, such as a loan or credit card, lenders will ask for your monthly debt obligations and monthly income so they can calculate your DTI. This helps them decide whether you’re in a position to handle more monthly debt payments. A low debt-to-income ratio makes you a better, less risky candidate and theoretically improves your odds of being approved. (Other factors, such as your credit score, also matter.)
What’s Included in Debt-to-Income?
To calculate your monthly debt, lenders look at mortgage or rent payments, credit card payments, student loan, auto, and other loan payments, as well as monthly child support or alimony payments. Not included are expenses such as utilities, cable and phone bills, health insurance, food, etc.
Gross monthly income is the average amount of money you make every month before taxes and other deductions are taken out. This can include wages, bonuses, overtime, dividends and freelance income, alimony, etc.
What Are the Two Types of Debt-to-Income?
Lenders typically divide the debt portion of your DTI ratio into two types: front-end and back-end.
The front-end DTI ratio reflects how much of your gross monthly income is going toward housing. Lenders generally like to see a front-end DTI of 28% or lower.
Back-end DTI reflects how much of your gross income is going toward other types of debt like car loans, personal loans, credit cards, and the like. Lenders prefer borrowers with a back-end DTI of 36% or below.
Most lenders primarily look at back-end DTI because it presents the most accurate account of your recurring monthly costs. But mortgage lenders typically use both. Different lenders and loan products will have different DTI limits.
How Does Your Debt-to-Income Ratio Affect Your Ability to Qualify for a Mortgage?
Simply put, the higher your debt-to-income ratio, the greater the risk you will not be approved for a home loan. According to a study conducted by NerdWallet, a high debt-to-income ratio was the most common reason for mortgage denials in 2020. The vast majority of those who were denied had a DTI of 50% or above. It’s worth noting that different types of home loans (e.g. conventional vs. USDA, etc.) may have different DTI maximums.
Your debt-to-income ratio might also serve as an indicator to you as to how much of a monthly house payment you can comfortably afford.
What Is a Good Debt-to-Income Ratio?
Standards differ from lender to lender, but a lower DTI is better. Most lenders like to see a debt-to-income ratio at or below 36%. Keeping your DTI at or below this figure can improve your chances of getting approved for a loan with more favorable terms. For example, if your gross monthly income is $3,000, you’d want your debt payments to be at or below $1,080 per month. While standards and guidelines vary, some mortgage lenders allow a debt-to-income ratio of up to 43-45%, and some FHA-insured loans allow up to 50%.
If your DTI is high, a lender may compensate for the higher risk by charging you a higher interest rate. If your loan payments consume half or more of your monthly income, that may be a sign you have more debt than you can handle and lenders may deny your application.
What Are the Best Ways to Improve Your Debt-to-Income Ratio?
A lower debt-to-income ratio can help you borrow more money from lenders and secure better credit terms. Since your DTI ratio is essentially what you owe every month divided by what you earn every month, the best way to improve it is to owe less or make more. This often takes careful planning, discipline, and patience.
Create a monthly budge with a line item for paying down your debt and stick to it. You might also consider postponing large purchases and consider taking on a side gig to increase your monthly income.
You May Also Like
Related Articles
Getting approved for a personal loan depends on more than just your credit score. Lenders look at your full financial picture—income, existing debt, application accuracy, and the amount you're requesting. Understanding these factors can help consumers better understand what lenders may consider when evaluating an application.
When people worry about debt consolidation hurting their credit, they’re usually thinking about how a loan application affects their credit score. What may negatively affect a credit score is a missed payment, a closed account that shortens your credit history, or new spending on the cards you just paid off.
When you consider taking out a personal loan, there are two ways in which your rate can be structured. The choice affects not just your monthly payment, but the total cost of borrowing over the full term, particularly if your loan runs several years.
Most people who experience a loan delay don't see it coming. The process feels straightforward—fill in the details, upload the documents, wait for approval. In most cases, it indeed is. But small gaps in an application can pause things at any stage, and the fixes are simpler than most people expect.
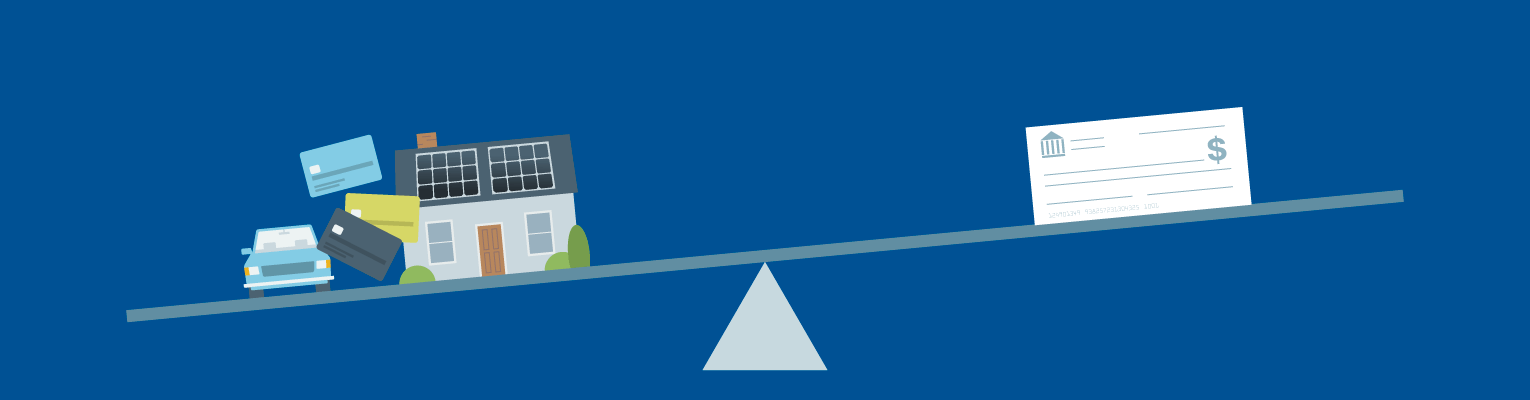
Your DTI ratio changes when your debts change, when your income changes, or both. There are concrete steps you can take before you apply that can move it in the right direction. In this article, we cover what the metric is, what the generally accepted thresholds look like, and how to lower it.
Related Impact
Today, we are thrilled to announce the completion of our acquisition of Radius Bancorp, Inc. (“Radius”). In February 2020, we announced our intent to acquire Radius and shared how we can grow and deepen our customer relationships with a marketplace bank.
Today, we are thrilled to announce the completion of our acquisition of Radius Bancorp, Inc. (“Radius”). In February 2020, we announced our intent to acquire Radius and shared how we can grow and deepen our customer relationships with a marketplace bank.
Related FAQ's
You can view and manage most of your account information by signing in on the web or using the Happen Bank mobile app, including your password, phone number, physical address, loan documents, payment methods, and two-factor authentication settings.
Personal Banking Customers: Our Elite and Reserve Tier customers can place a wire via Online banking or the Happen Bank Mobile app. For all other customers, they can reach out to Customer Service at 800.242.0272 to initiate a wire.
The Society for Worldwide Interbank Financial Telecommunication (SWIFT) Code is a unique identification code that may be required by some banks, broker-dealers, and investment managers for the completion of international wire transfers.
Contact our team at 833-498-1399.
LevelUp Savings is a high-yield savings account that rewards you with a higher LevelUp Rate when you make deposits of at least $250 per statement cycle.
Related Glossary
{noun} A type of credit that allows the borrower to make charges and payments against a set borrowing limit, paying interest only on outstanding balances.
{noun} The amount of unpaid interest that has accumulated as of a specific date, either on a loan or an interest-bearing account or investment.
{noun} The total annual cost to borrow money, including fees, expressed as a percentage.
A debt that is written off as a loss because the financial institution or creditor believes it is no longer collectible due to a substantial period of nonpayment.
{noun} An interest rate that remains the same for a set time, usually for the life of the loan.